Homebuyers
620+ typically needed for FHA
Underwriters do not care why the item is there — only what the file says. We clean up what is wrong on it so your mortgage application is judged on the real picture.
Digion Advisory is a credit restoration firm for people who keep getting declined for reasons that are not accurate. We audit all three bureau reports and challenge the collections, charge-offs, hard inquiries and late payments that your file cannot actually support.
from 600+ clients across all 50 states
Live client file
Month 6 · after 4 dispute rounds
Experian
765
Equifax
759
TransUnion
763
We work directly with the reporting system
Services
Most people assume an item they genuinely owed is untouchable. It is not. The law tests whether the company reporting it can verify every field it put on your file — not whether the debt was real. That is a very different bar, and a great many furnishers cannot clear it.
Collection accounts are one of the most frequently mis-reported items on a credit file — wrong balances, missing validation, duplicate listings across agencies.
We pull all three reports, document every collection line item, and challenge the ones that are inaccurate, incomplete or unverifiable directly with the bureaus and the furnisher under the FCRA.
A charge-off can sit on your report for seven years and quietly cost you every approval you apply for — often with reporting errors attached to it.
We verify the charge-off date, the reported balance, the payment history grid and the status codes. Where the furnisher cannot substantiate what it reported, we escalate until the file is corrected.
Hard inquiries you never authorised — or that were never converted into an account — can stack up and drag your score down for two full years.
We identify unauthorised and unrecognised pulls, prepare the documentation the bureaus require, and challenge each one on your behalf so your file only reflects credit you actually applied for.
Payment history is roughly 35% of your score. A single inaccurately reported 30-day late can undo months of disciplined payments.
We reconstruct your true payment history from statements and records, then challenge any late marker the data does not support — including lates reported after a settlement or during forbearance.
Bankruptcies, judgments, tax liens and repossessions carry the heaviest weight on a file — and the strictest reporting standards.
Because these items are held to a higher verification bar, we audit them against the public record itself and challenge anything reported beyond what the source actually supports.
Mixed credit files and identity theft put someone else's debt on your name — and the bureaus will not fix it until someone pushes properly.
We separate merged files, file identity-theft blocks where applicable, and lock the corrections in so the same accounts do not reappear on the next refresh.
The part nobody explains
This is the question everyone asks before they hire anyone, so here is the honest answer — and it is better than you expect.
Accurate and verifiable are not the same word. The Fair Credit Reporting Act does not ask whether you once owed the money. It asks whether the company reporting it can prove, inside thirty days, that every field it put on your file is complete, current and correct — and that it was reported to the Metro 2 standard the bureaus themselves require.
Those are separate tests, and the furnisher has to pass all of them. In practice they often cannot. The date of first delinquency does not match across the three bureaus. The balance contradicts their own statements. The status code is wrong for the account type. The debt was sold twice and nobody kept the paperwork. Any one of those is grounds for deletion — on a debt you genuinely owed.
So when a collection or a charge-off is the one thing standing between you and a mortgage approval, it is worth putting through that process properly rather than waiting seven years for it to age off.
Across the files we have worked
8 in 10
accurate-but-flawed items came off once they were challenged on verifiability rather than on the debt itself. That is what we have seen — not a promise of what your file will do.
Who we help
A declined application is rarely about who you are today. It is about what a file says about you — and files are wrong more often than anyone admits.
Underwriters do not care why the item is there — only what the file says. We clean up what is wrong on it so your mortgage application is judged on the real picture.
Dealerships shop one application across a dozen lenders and leave a wall of hard inquiries behind. We challenge the pulls you never authorised.
Personal credit still gates most small business funding. We clean the personal file first, then map the path to a business credit profile that stands on its own.
Someone else's debt should not be your problem. We separate merged files, file identity-theft blocks, and make the corrections stick past the next refresh.
The process
You will always know what was sent, what came back, and what it changed. It is pushed to you every week, without you ever having to ask for it.
Step One
That is the whole ask. No fee, no card, no call you have to sit through first — just your three-bureau credit report. If you do not have one, we will point you at where to pull it free in about two minutes.
14 negative items found
11 negative items found
13 negative items found
Step Two
A written plan built on your actual file: every item we intend to challenge, the grounds we will challenge it on, and the route to a 750+ score and the approval you are after. Pricing is in the plan and it is specific to you, because no two files take the same work.
Your plan · item by item
Step Three
You approve the plan and we start that week. Rounds go to the bureaus and to the furnishers themselves, and we escalate the moment anyone rubber-stamps a verification. Most clients see their first deletions land in 22 to 27 days.
Dispute rounds · live tracking
Step Four
No third-party credit monitoring to subscribe to. We push your progress to you every week by email and SMS — what went out, what came back, what changed — and support is there whenever you need it.
Your weekly update · score trend
763
Results
These are averages from our own client files, not projections. Your file is its own case — we will give you an honest read on it before you pay anything.
0+
Average point increase
across clients completing 6 months
0+
Items challenged
across all three bureaus
0%
Clients see movement
within the first two dispute rounds
0
States served
fully remote, fully documented
Anatomy of one file
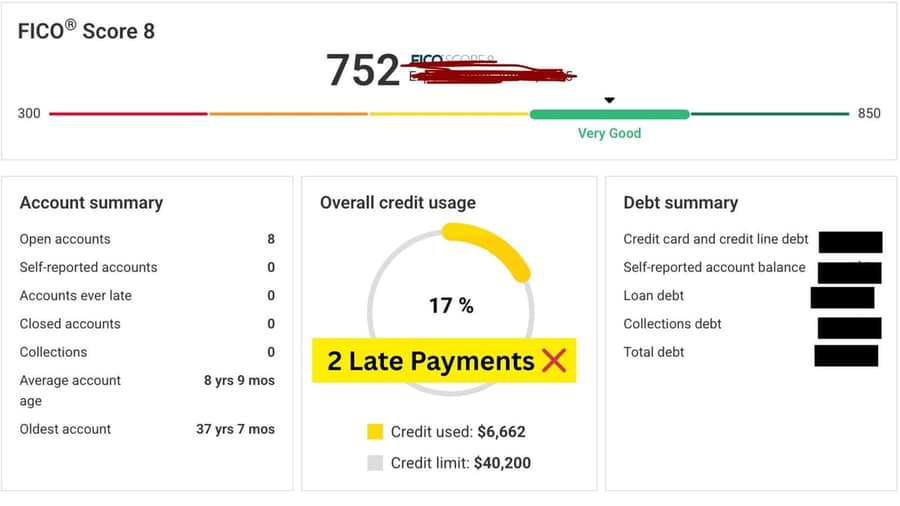
This is the client's own dashboard, not a mock-up. The account summary now reads zero accounts ever late and zero collections — on a file that came to us with both. Eight open accounts, utilisation at 17%, oldest line 37 years.
One client's file. Individual results vary, and nothing here is a promise of a specific outcome on yours.
Receipts
These are real client files and real messages, shared with permission. Names and photos are redacted — the numbers are untouched.
Every screenshot shows one individual's file. Results depend on what is actually on your report and are not a promise that you will see the same movement. Digion Advisory does not remove accurate, current and verifiable information from a credit report.
What it costs
We cannot put one number on a page honestly, because we have not read your report yet. What we can do is show you exactly how the number is worked out — and where it has landed for most people.
What the number depends on
Most files land between
$1,000–$1,500
Paid as the work is performed — never before it.
Always included, whatever your number is
Reading your report and building the plan costs you nothing. You see your price written into that plan before you agree to anything, and under the Credit Repair Organizations Act we cannot charge you before services are performed.
Partner programme
If you are a realtor, loan officer, car dealer, insurance agent or creator, you already meet people who get declined. Send them here and you keep 40% of the revenue on every file — on an average file of $1,000 to $1,500, tracked in your own dashboard and paid on the 1st.
Fifteen minutes. Tell us who you serve. No fee, no minimum, no exclusivity.
A tracked link and a marketing kit land in your inbox the same day.
Everyone who comes through your link is attributed to you for life.
40% of the revenue on every file, cleared on the 1st of the month.
Commission calculator
You earn per month
$2,400 – $3,600
Over 12 months
$28,800 – $43,200
Illustrative only. The range assumes an average file of $1,000 to $1,500; what you actually earn depends on how many of your referrals go ahead and what their files need.
Why partners stay
0%
Of every file you send
0st
Payout each month
0
Cost to join
What a partner gets
40%
of every file you send
Not a flat finder's fee. Your cut is a share of what the client actually pays, on an average file of $1,000 to $1,500.
Every client
tracked, start to finish
You see each person you sent, where they are in the process, and what you have earned this month.
The 1st
bank transfer or PayPal
Commissions clear on the first of the month. Nothing to chase, nothing to invoice.
Clients & partners
Four collections and two charge-offs that were not even mine. Digion documented every one of them and stayed on the bureaus for five months. I closed on my house in March.
I had eleven hard inquiries from one dealership shopping my application around. Nine of them came off. My rate on the refinance dropped by almost two points.
What I actually valued was the honesty. They told me straight which items were accurate and were not going anywhere, and focused on the ones that were wrong.
I send my declined mortgage clients to Digion and keep 40% of every file. Last quarter it covered my office rent twice over. The partner dashboard is genuinely good — I can see exactly where each client is.
Testimonials reflect individual experiences. They are not a guarantee that you will achieve the same result.
Free credit audit
Tell us where your credit is now and what you are trying to get approved for. We read the file and send back a written plan — every item we would challenge, the grounds, and the route to a 750+ score. No fee to find out.